BUYING IN GEORGIA? START HERE.
Your income may look different.
Your path to homeownership can too.
Whether you earn a W-2, own a business, work for yourself, or have income that doesn't fit neatly into a box, you may have more financing options than you realize.
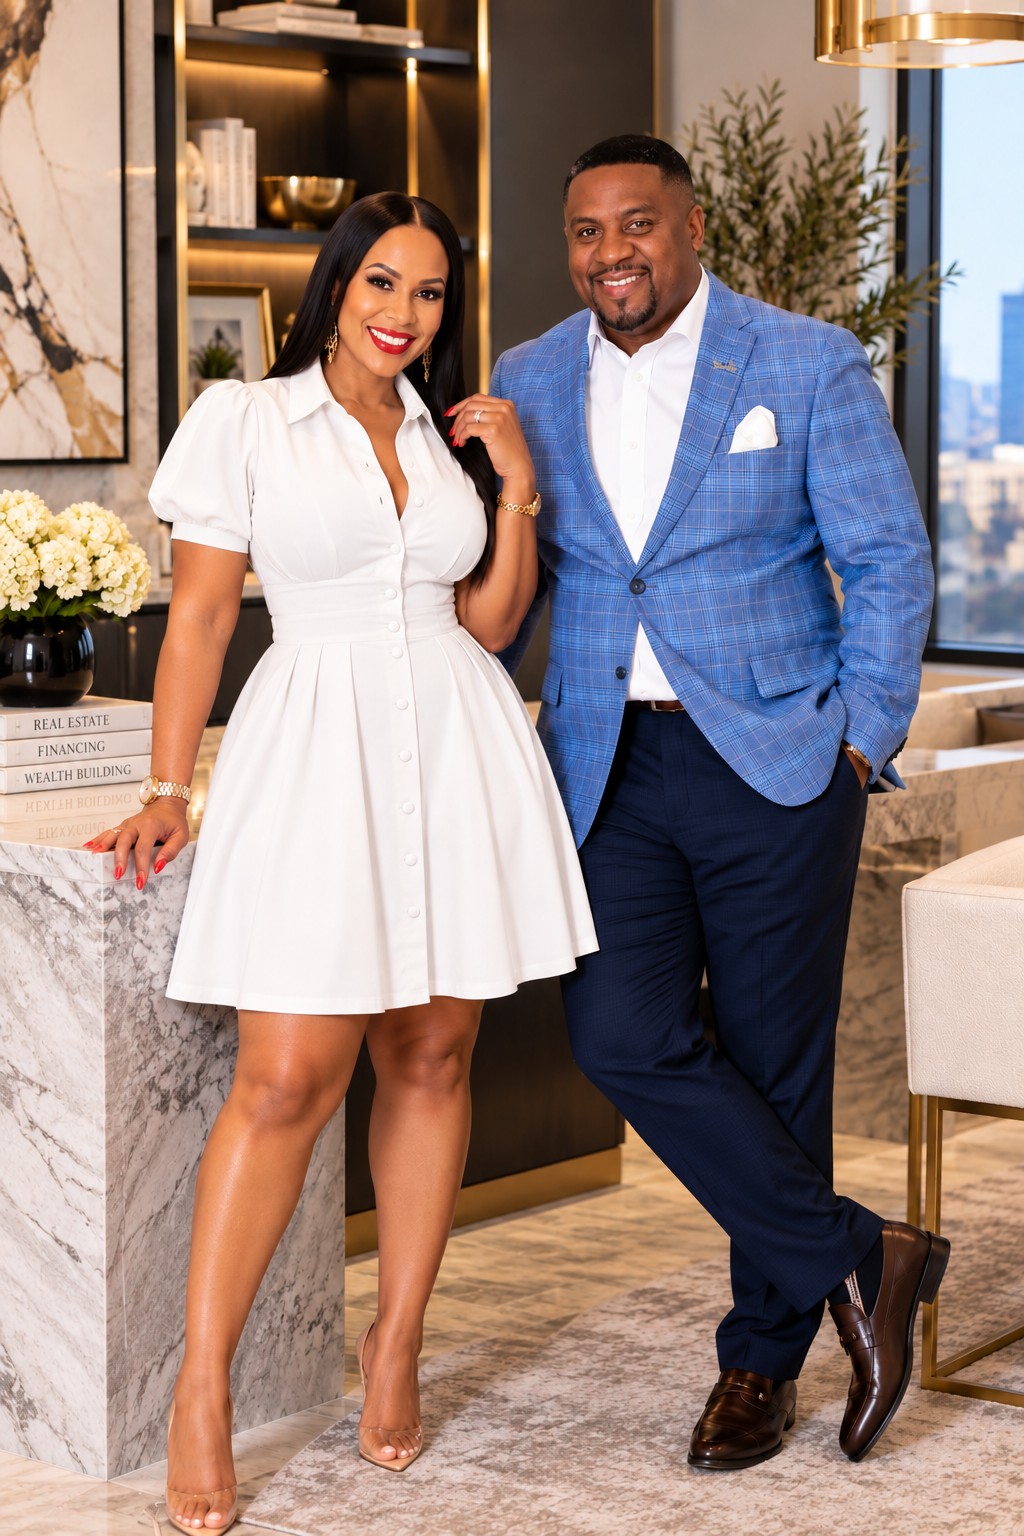
REAL ESTATE + FINANCING, WORKING TOGETHER.
This page is specifically for buyers purchasing in Georgia. Reginald serves Georgia and offers a broad range of mortgage programs. Purchasing in Louisiana instead? Visit the Louisiana financing page.
Conventional · FHA · VA · Down Payment Assistance · Bank Statement · P&L · 1099 · Self-Employed · Investor & Specialty Programs
A DIFFERENT STARTING POINT
Been told your income makes buying a home complicated?
That doesn't necessarily mean homeownership is off the table.
Traditional financing works well for many buyers. But business owners, entrepreneurs, independent contractors and other buyers sometimes need a different way to document income.
That's why Brittny and Reginald bring the real estate and financing conversations together from the beginning.
Let's figure out the financing first. Then let's go find the house.
Traditional
Financing
For qualifying buyers whose income and documentation fit a more traditional lending path.
- Conventional
- FHA
- VA
- Down payment assistance
- Other qualifying traditional programs
Bank Statement
Loans
For qualifying self-employed borrowers whose deposits may provide a better picture of their income than traditional tax-return calculations.
VIEW PROGRAM DETAILS
- 12 or 24 months of business, personal, or combined statements
- Minimum 620 FICO; no-score options may be available
- Up to 90% financing on a primary home
- Loan amounts up to $4 million
- Primary, second home, investment property, purchase, refinance, cash-out and condo options as described in the program material
- Tax returns, W-2s, 1099s and pay stubs are not required under this program
P&L
Financing
For qualifying established business owners who may be able to use an eligible profit-and-loss statement for income qualification.
VIEW PROGRAM DETAILS
- 1-year or 2-year P&L; self-prepared P&Ls are not accepted
- Minimum 660 FICO
- Up to 80% financing on a primary home
- Loan amounts up to $2.5 million
- Primary, second home, investment property, purchase, refinance and cash-out options
- Debt-to-income up to 55% on a primary home as described in program material
- At up to 70% loan-to-value, bank statements are not required as described in program material
Program details, rates, terms, loan amounts, credit requirements, down payment requirements and availability are subject to lender guidelines, underwriting, borrower qualifications, property eligibility and change. Not all applicants will qualify.
WHEN YOUR TAX RETURN DOESN'T TELL THE WHOLE STORY
YOU BUILT YOUR BUSINESS TO KEEP MORE OF WHAT YOU EARN.
YOUR MORTGAGE OPTIONS SHOULDN'T IGNORE THE BIGGER PICTURE.
Business owners may legitimately use deductions that reduce taxable income, which can sometimes make traditional mortgage qualification more complicated.
That does not mean something is wrong with your finances. Eligible borrowers may have alternative documentation options, including bank statement and P&L programs. Reginald can help you understand which path may fit your situation.
EXPLORE FINANCING OPTIONSREAL ESTATE + FINANCING
ONE GAME PLAN.
Two professionals working together so your home search starts with a clear financial strategy.
YOUR REALTOR
Brittny McKay
REALTOR | Keller Williams Cityside
Home search, property strategy, offer strategy, negotiations, and contract-to-closing real estate guidance.
Georgia License #377490Direct: 504-236-5749
brittny@brittnymckay.com
YOUR MORTGAGE BANKER
Reginald Masters
Mortgage Banker | Masters Home Mortgage
Financing strategy, pre-qualification/pre-approval, loan program selection, mortgage process, and financing through closing.
NMLS #833985 | Masters Home Mortgage NMLS #1643634678-938-7932
reginald@mhmteam.com
Brittny McKay/Keller Williams Cityside and Masters Home Mortgage are separate companies. Consumers are not required to use either professional or company in order to work with the other.
HOW IT WORKS
A clear path from plan to home.
UNDERSTAND YOUR OPTIONS
We'll look at your goals, income structure and homebuying plans to determine which financing path may make sense.
GET FINANCING READY
Work with Reginald to complete the appropriate financing process and understand your purchasing power.
FIND YOUR GEORGIA HOME
Once financing is in place, work with Brittny to identify the right property, prepare a competitive offer and navigate the transaction.
READY TO GET STARTED?
Let's create a plan that fits your goals.
Choose the next step that fits where you are today. Mortgage applications and financial documents stay within Reginald's secure process.
GEORGIA BUYER INQUIRY
START YOUR HOME SEARCH PLAN.
This form is for Brittny's real-estate team. Please do not include SSNs, account numbers, bank statements, tax returns or other financial documents.
FAQ
Clear answers before your next move.
Can I buy a home if I'm self-employed?
Possibly. Qualification depends on your complete financial picture and the lender program. Starting with a financing conversation helps identify the options that may fit.
Do I need tax returns for every mortgage program?
Not for every program. Traditional financing may use tax returns, while certain alternative-documentation programs have different requirements. Reginald can review the appropriate path for your scenario.
What is a bank statement mortgage?
For eligible self-employed borrowers, a bank statement program may use qualifying deposits from 12 or 24 months of statements rather than relying solely on traditional tax-return income calculations.
What is a P&L mortgage program?
Eligible established business owners may have an option using a qualifying 1-year or 2-year profit-and-loss statement prepared and reviewed by an appropriate qualified professional. Self-prepared P&Ls are not accepted.
Do you offer FHA, VA and conventional financing?
Yes. Reginald can discuss available conventional, FHA, VA and other qualifying traditional mortgage programs, subject to lender guidelines and borrower qualifications.
Are down payment assistance programs available?
Potential availability depends on the program, property, location and borrower qualifications. Reginald can discuss current options that may apply to you.
Should I talk to the lender before looking at homes?
Yes. Getting financing-ready first helps clarify purchasing power and lets Brittny tailor your home search and offer strategy around a realistic plan.
Can Brittny help me anywhere in Georgia?
Brittny is licensed in Georgia and can discuss your homebuying goals and service area.